What We Learned Restructuring the Team Mid-Growth
A restructure takes an afternoon to design and a year to judge. What we learned in the year: change versus transition, the neutral-zone dip, and the 30-90-180 Check.
Read article

Written by
David
Head of Operations
Published September 29, 2026
Every iGaming number has a counterpart that keeps it honest. Read them in pairs and they answer the question finance asks about every campaign: when does a depositor pay back?
< FTD > is a player's first real-money deposit.
< GGR > is what players lose: stakes minus winnings.
< NGR > is GGR after bonuses, taxes, fees, and other agreed deductions.
< CPA > is what you paid to acquire a single depositor, and payback is the month when that depositor's NGR finally covers it.
Those definitions fit in a paragraph. The trouble starts when a number travels without its counterpart.
So when a sportsbook deck quotes GGR, it is quoting a figure at least 54% larger than the NGR that revenue share and payback are calculated on.
This AP Collective guide covers the numbers themselves and how they add up to payback, written for crypto casino and sportsbook teams competing with licensed operators. Deciding how to pay creators and affiliates on these numbers? Read our iGaming influencer marketing guide to payouts and attribution. Choosing a partner to run acquisition? See our ranking of iGaming marketing agencies.
FTD, GGR, NGR and CPA are the 4 numbers most iGaming marketing reports are built on. Each has a simple formula and a counterpart that tells you whether the formula is flattering you. Here they are with the supporting metrics that sit between them.
Metric | What It Measures | Formula | Its Counterpart |
|---|---|---|---|
Handle | Total amount staked | Sum of all bets placed | GGR |
Deposits | Money players put into their accounts | Sum of deposits in a period | GGR per deposited dollar |
Hold | Share of handle the operator keeps | GGR ÷ handle | Hold after promotions |
GGR | Player losses | Stakes minus winnings paid | NGR |
NGR | Revenue left from play | GGR minus bonuses, taxes, fees and other agreed deductions | NGR after revenue share |
FTD | A player's first real-money deposit | Count of first deposits in a period | FTD quality |
CPA | Fee paid per acquired depositor | Acquisition payouts ÷ qualified FTDs | Fully loaded CAC |
CAC | Every cost of acquiring a depositor | All acquisition costs ÷ FTDs | NGR per FTD |
Payback | Time taken to recover CAC | First month cumulative NGR per FTD ≥ CAC | Share of the cohort that has paid back |
The formulas are rarely where disputes start. Disputes start in the deductions and the denominators: which costs come off GGR and whether NGR is divided by every depositor or only by those still playing.
Scale puts the first pair in context. US commercial sportsbooks took $166.94bn in bets in 2025 and kept $16.96bn, a hold of about 10.2%, while online casino revenue rose 27.6% to $10.74bn, according to the American Gaming Association's 2025 revenue release. A sportsbook reporting handle is reporting a number roughly 10x its revenue.
The Payback Pairs is AP Collective's framework for iGaming reporting: 5 metric pairs, read in the order the money moves, where the second number in each pair keeps the first one honest.
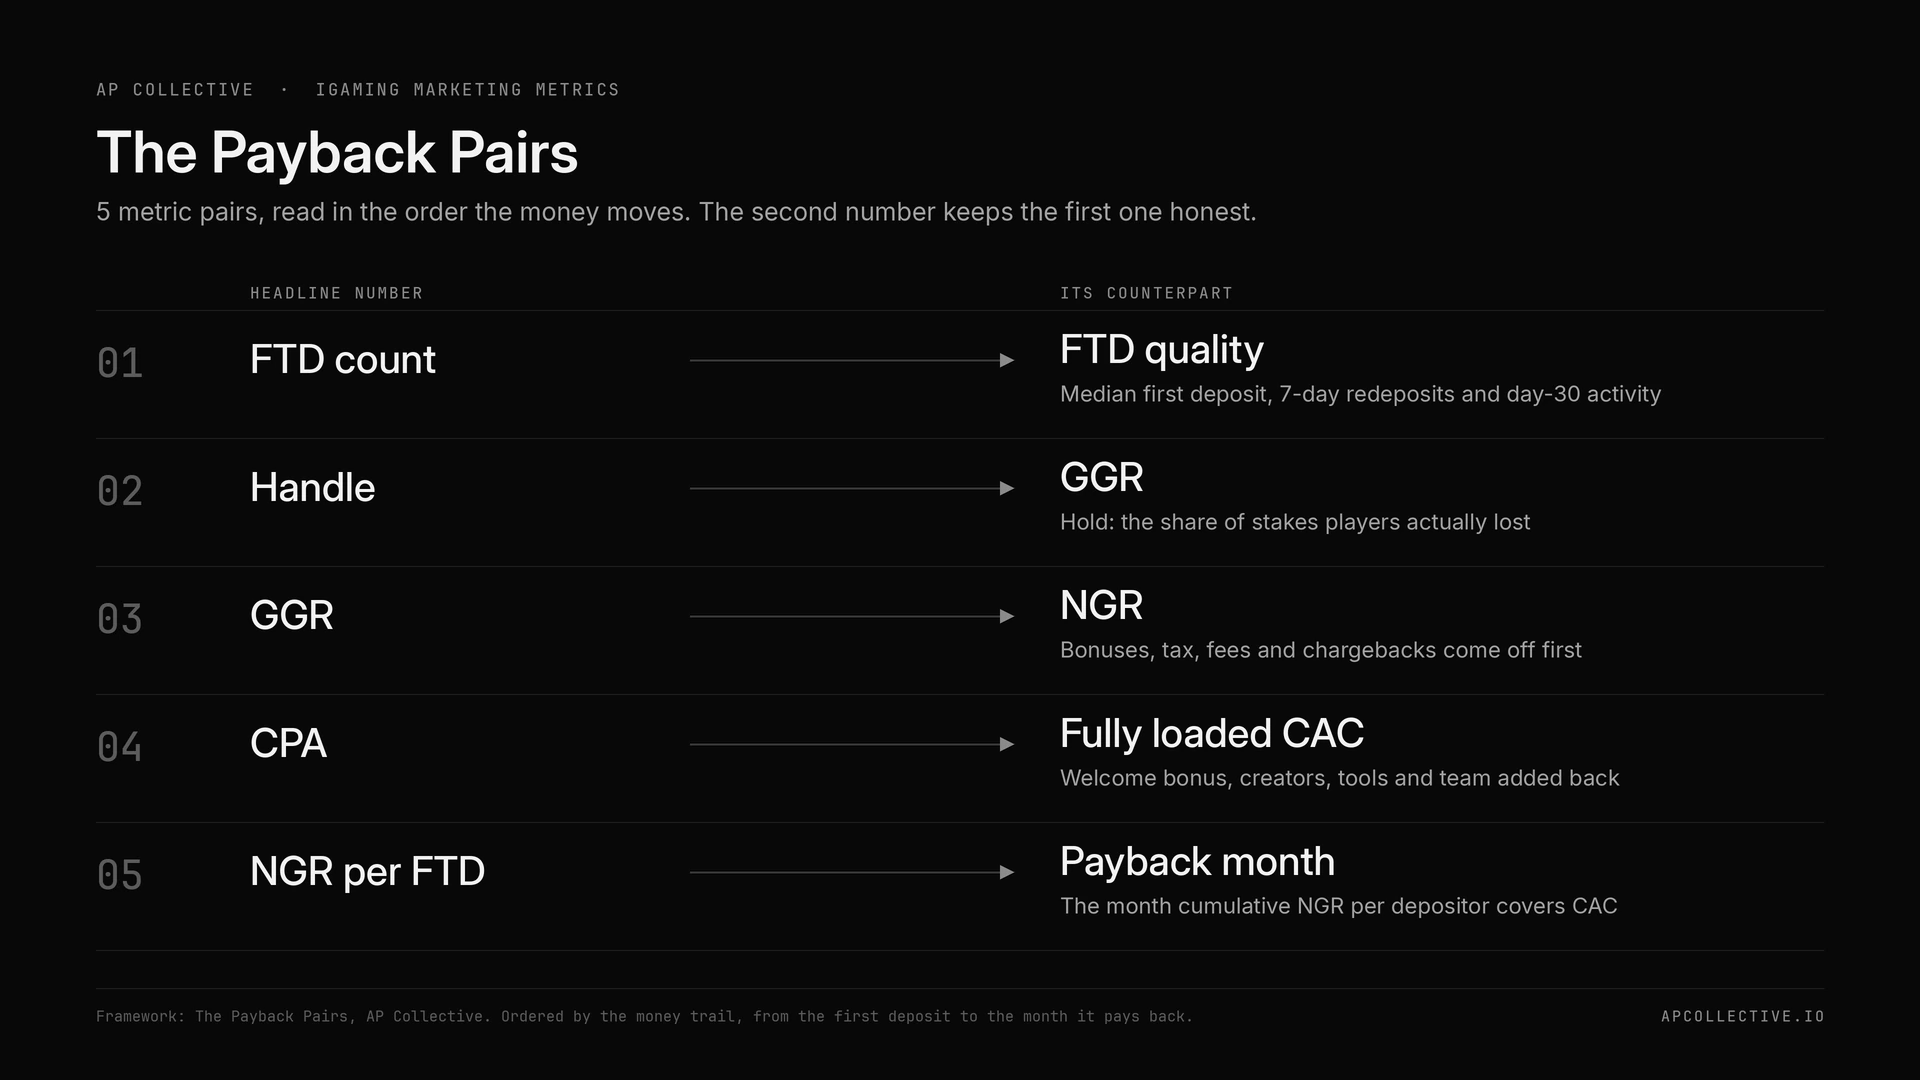 The Payback Pairs framework showing 5 iGaming metric pairs from FTD count to payback month
Ordering logic, stated plainly: the pairs follow the money, from the first deposit to the month that deposit pays back. They are not ranked by importance. A report that shows the first number of a pair without the second is a claim; with both, it is a result.
Why bother with pairs when a single headline number is easier to present?
Because a headline number can move in the opposite direction to the value it is meant to represent.
An FTD count overstates your player base because it counts every first deposit equally, and most first depositors never become regular players. FTD, or first-time deposit, is the moment a registered user funds a real-money account for the first time. Listed affiliates call the same event an NDC, a new depositing customer. It triggers most CPA payouts. It is also one of the easiest numbers in the funnel to game, because a first deposit can be as small as the cashier minimum and still count in full.
Most depositors stay small. In the Patterns of Play study of about 140,000 British online gambling accounts, 85% of betting accounts spent less than £200 on betting across a full year, as iGaming Business reported from the GambleAware-commissioned research. An FTD count adds a £10 depositor and a £10,000 depositor together and calls the result 2.
So pair the count with quality counterparts, each read at a fixed point after the deposit:
The question that sorts good acquisition from bad fastest is also the one most dashboards cannot answer: how many of last month's FTDs made a second deposit?
Crypto operators need an extra rule. A crypto FTD is usually the first on-chain deposit to a player's assigned address, often in USDT, and minimums can be tiny. Set a qualifying floor in US dollars, valued at the time of deposit, or a creator campaign can post hundreds of FTDs that together would not cover a single CPA fee.
If your iGaming reporting starts and ends with FTD counts, AP Collective can rebuild it around depositor quality and payback, with cohort tracking that shows which creators and channels send players who come back to deposit again. See competitive intelligence or talk to the team.
Handle is the total amount staked and GGR is the part of it players lose, so a sportsbook's GGR is usually around a tenth of its handle and a casino's is a far smaller share of its turnover. Hold is the counterpart that converts one into the other: GGR divided by handle.
US commercial sportsbooks held about 10.2% in 2025 on the AGA figures. Michigan's online sportsbooks held 12.4% of their $5.4bn handle before deductions and about 8.1% after them, our calculation from the Michigan Gaming Control Board's December 2025 revenue release and its annual report. Always ask whether a hold figure is gross or adjusted.
Handle can rise while revenue falls, and 2026 produced a clean public example. DraftKings grew Sports Consumer Volume, its name for handle, 14.5% to $13.14bn in Q2 2026. Its sports revenue fell 10.6% to $891.9m over the same period, and its sports net revenue margin dropped from 8.7% to 6.8%, according to DraftKings' Q2 2026 results filed with the SEC. Customer-friendly results and new customer promotions did the damage.
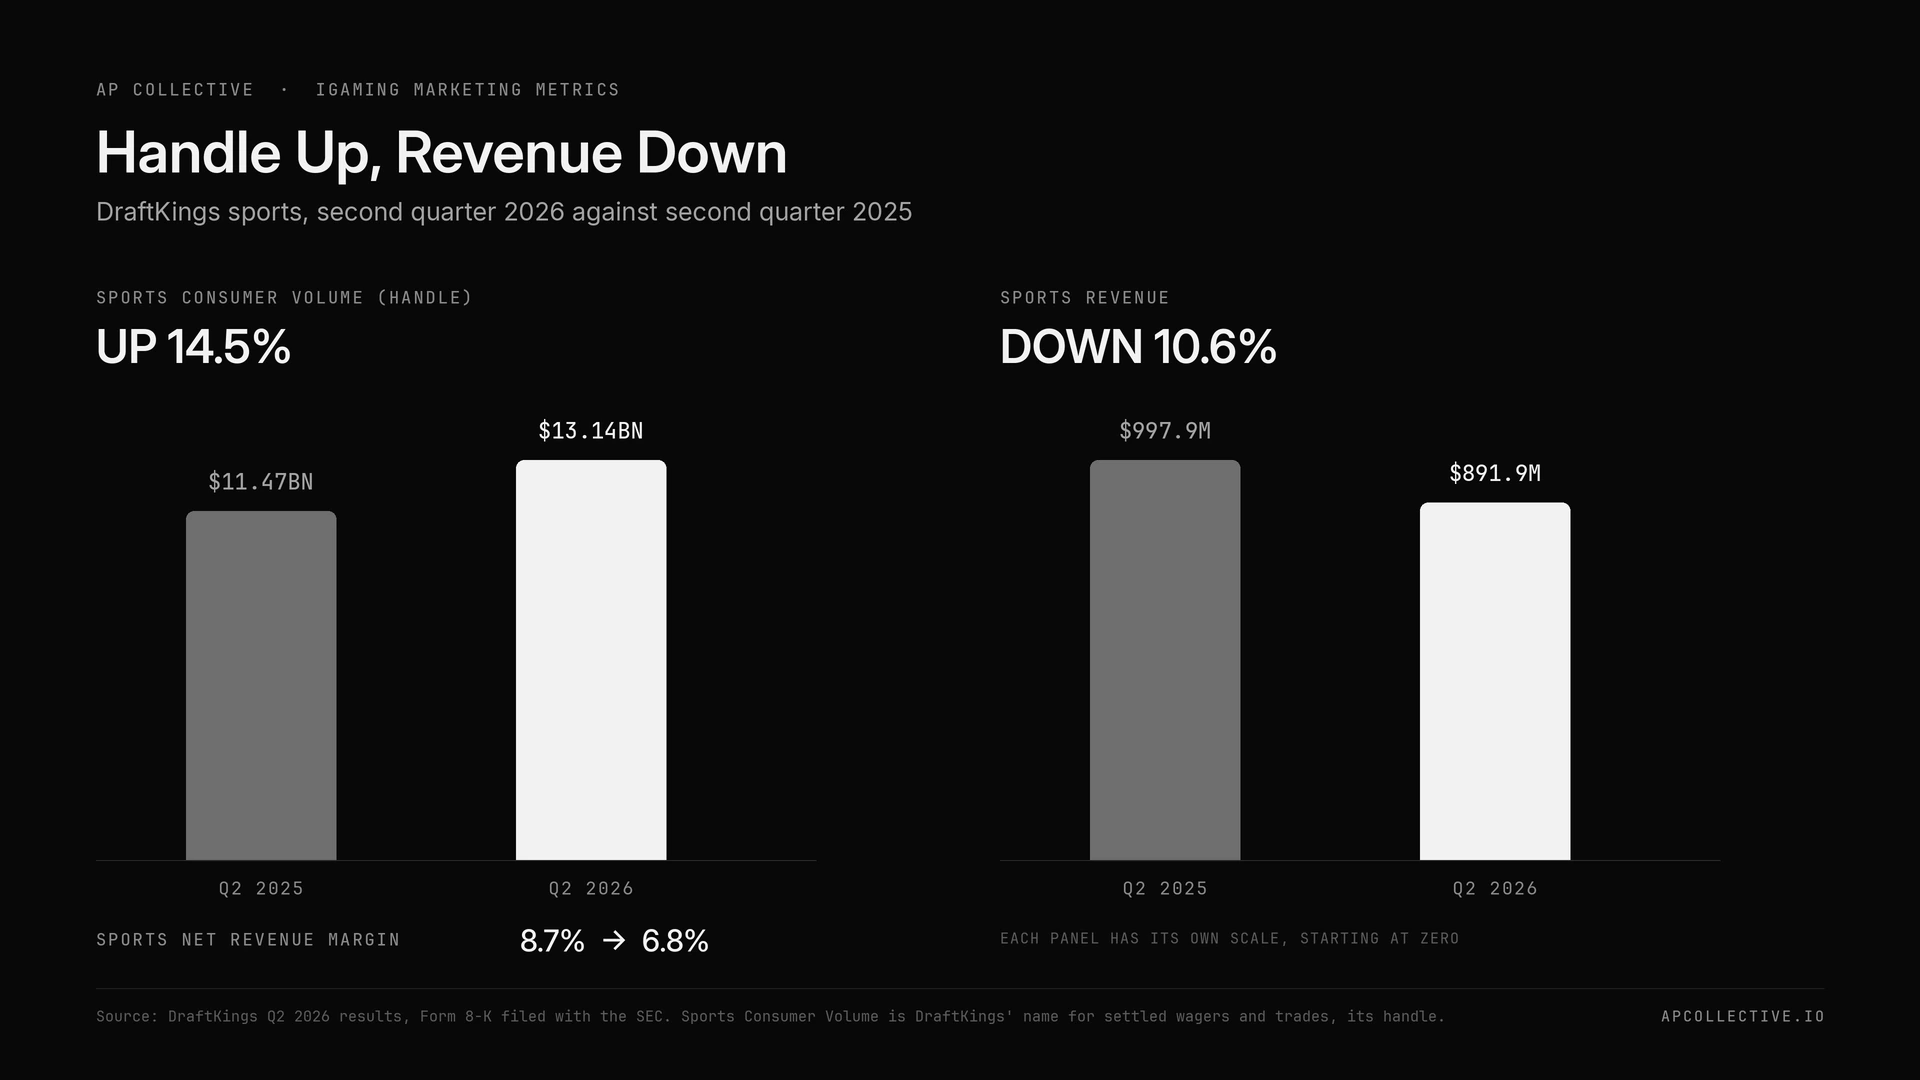 DraftKings Q2 2026 sports handle rose 14.5% while sports revenue fell 10.6% year over year
Crypto casinos have a harsher version of the same problem. Many publish total wagered as their headline growth figure, and wagered volume is the easiest number in iGaming to inflate, because bonus funds and rakeback both get staked again. A game with a 1% house edge turns $1bn wagered into roughly $10m of GGR before a single deduction.
Our advice: take wagered volume out of growth reports. Report deposits and GGR instead, with hold alongside. Wagered volume can climb for months while the operator loses money on the players generating it, and a board that sees it next to acquisition spend will draw the wrong conclusion every time.
NGR is GGR minus the costs of producing it: usually bonuses and free bets, gaming tax, payment fees, chargebacks, provider fees and jackpot contributions, in whatever combination the contract or the regulator specifies.
How big the gap gets depends on the product and on the rulebook. From the MGCB's 2025 annual report, Michigan's online sportsbooks deducted $235.4m of $671.3m in gross receipts before tax, 35.1%, and under the Lawful Sports Betting Act that deduction is the free play bettors wagered.
Online casinos deducted about $189m of $3.09bn, 6.1%. That figure reflects the law more than the promotions. The Lawful Internet Gaming Act caps the casino free play deduction: for operators that launched in 2021 the limit was 6% of gross receipts in 2025, falls to 4% in 2026 and disappears from 2027. In each month of 2025 we checked, from March to December, the casino deduction sat between 5.5% and 6.1% of gross receipts. The cap is doing the work. These are our own calculations from published MGCB figures (gross receipts minus adjusted gross receipts, divided by gross receipts), and we have not seen the split published elsewhere.
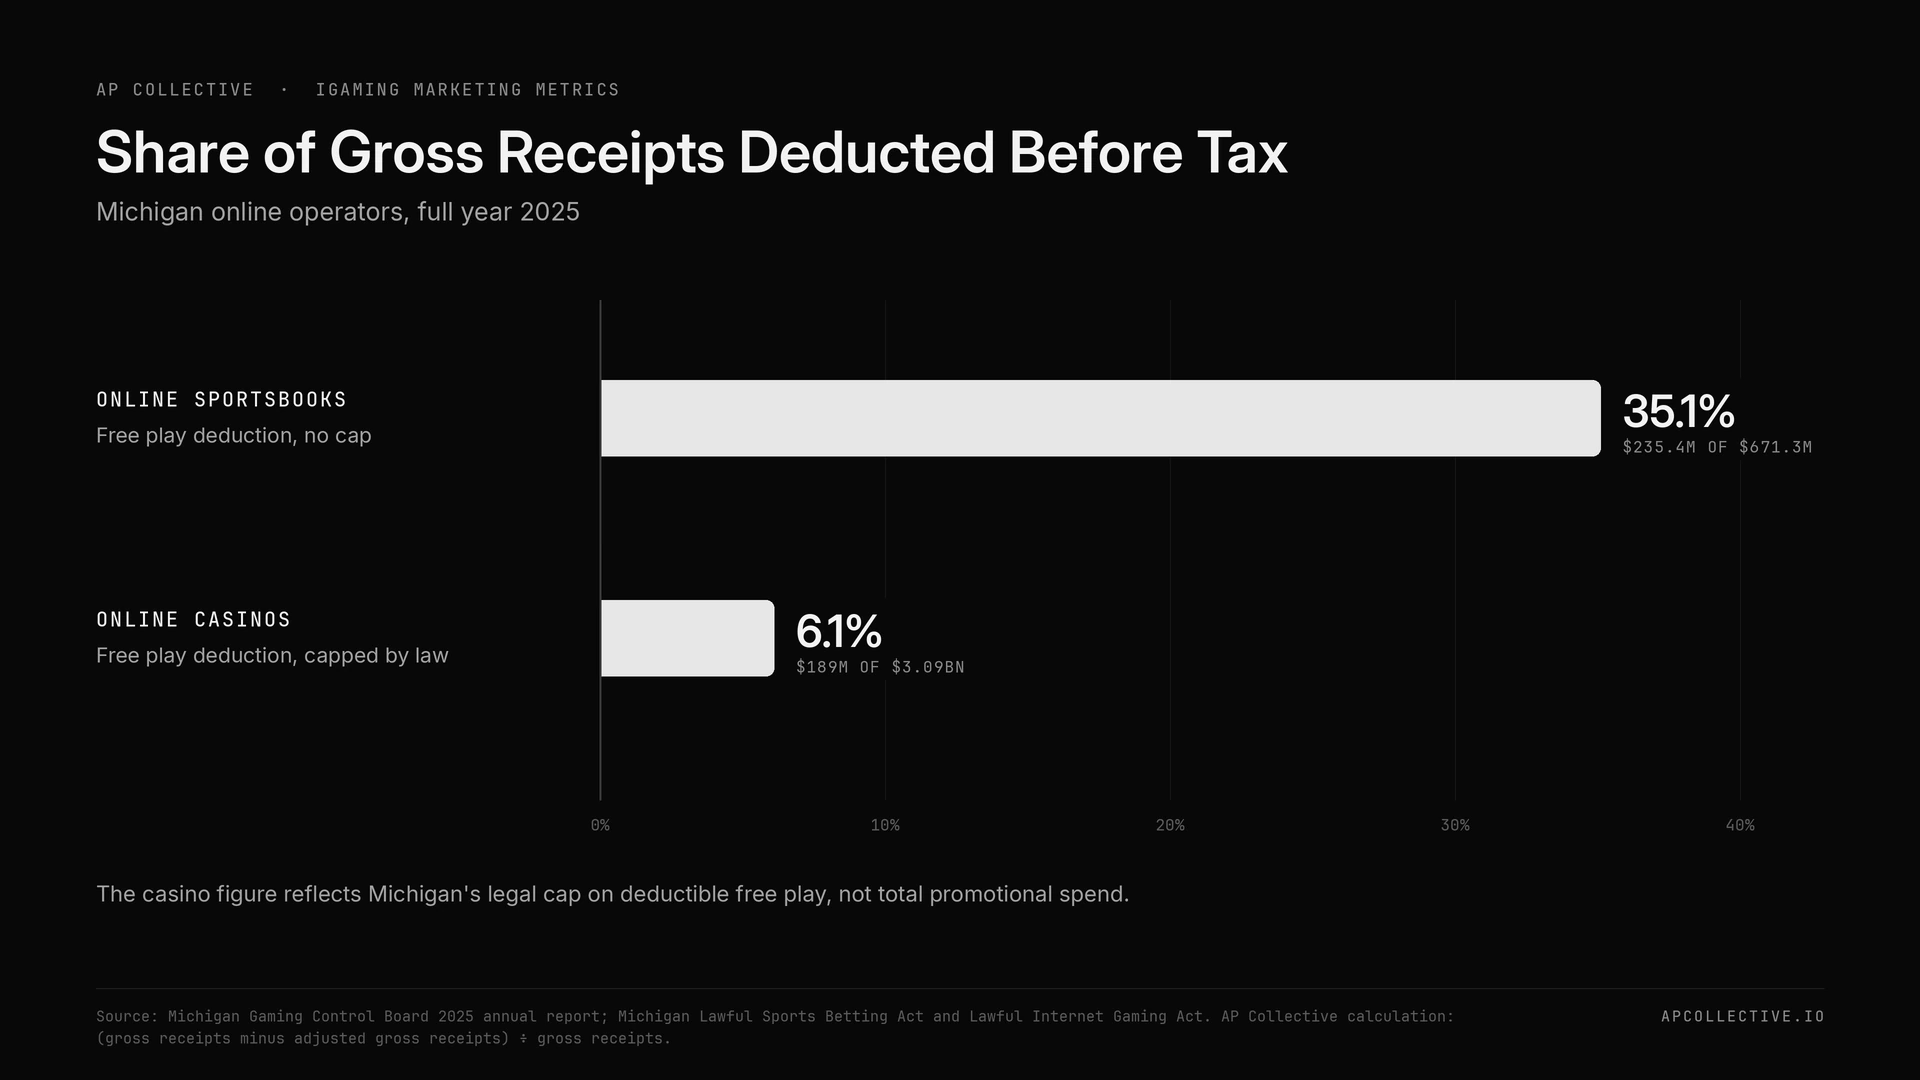 Michigan 2025 online sportsbooks deducted 35% of gross receipts versus 6% for online casinos
The comparison teaches 2 things. First, sportsbooks really do run on free bets: 35% of Michigan's online sportsbook GGR went back out as free play, so any revenue share or payback model built on sportsbook GGR inherits a large error. Second, a regulator's adjusted figure is a tax construct. The casino line stops at the legal cap while the casino's real bonus cost keeps going, so neither line is NGR.
Listed operators add a twist of their own. DraftKings records incentive awards as a reduction of revenue rather than as a marketing expense, per its 2025 annual report on Form 10-K. Its reported revenue already sits closer to NGR than to GGR, which matters the moment you benchmark a partner's NGR statement against a public company's numbers.
NGR has no single legal definition in affiliate contracts, so the deduction list is the formula. This is the list worth agreeing in writing before any revenue share starts.
Deduction | What It Covers | Ask Before You Sign |
|---|---|---|
Bonuses and free bets | Promotional value granted to players | Deducted when granted or when wagered? |
Gaming tax | Duty owed to the regulator | Charged on gross or on adjusted revenue? |
Payment fees | Deposit and withdrawal processing | Actual cost or a flat rate on deposits? |
Chargebacks and fraud | Reversed deposits and voided play | Clawed back from this cohort only? |
Provider and platform fees | Game studio and platform revenue share | Deducted at all, and at what rate? |
Rakeback and cashback | Loyalty returns, common in crypto casinos | Deducted from NGR or paid from margin? |
Admin fee | A flat charge some programmes add | What does it cover that other lines do not? |
CPA is the fee on the invoice for a qualified depositor, while fully loaded CAC is every cost of acquiring that depositor, including the welcome bonus that never appears on a marketing invoice. CPA, or cost per acquisition, is how affiliate and creator deals are priced. CAC, customer acquisition cost, is the operator's view: all acquisition spend divided by the depositors it produced.
Here is how an illustrative $200 CPA becomes a $360 CAC.
Cost Line | Per FTD | Where It Usually Shows Up |
|---|---|---|
CPA fee to the affiliate or creator | $200 | Marketing budget |
Welcome bonus and free bets consumed | $90 | Deducted from revenue |
Creator fees and creative | $25 | Marketing budget |
Tracking and attribution tools | $10 | Technology budget |
Team and agency time | $20 | Overhead |
Fraud and chargeback write-offs | $15 | Deducted from revenue |
Fully loaded CAC | $360 | Spread across 4 lines of the P&L |
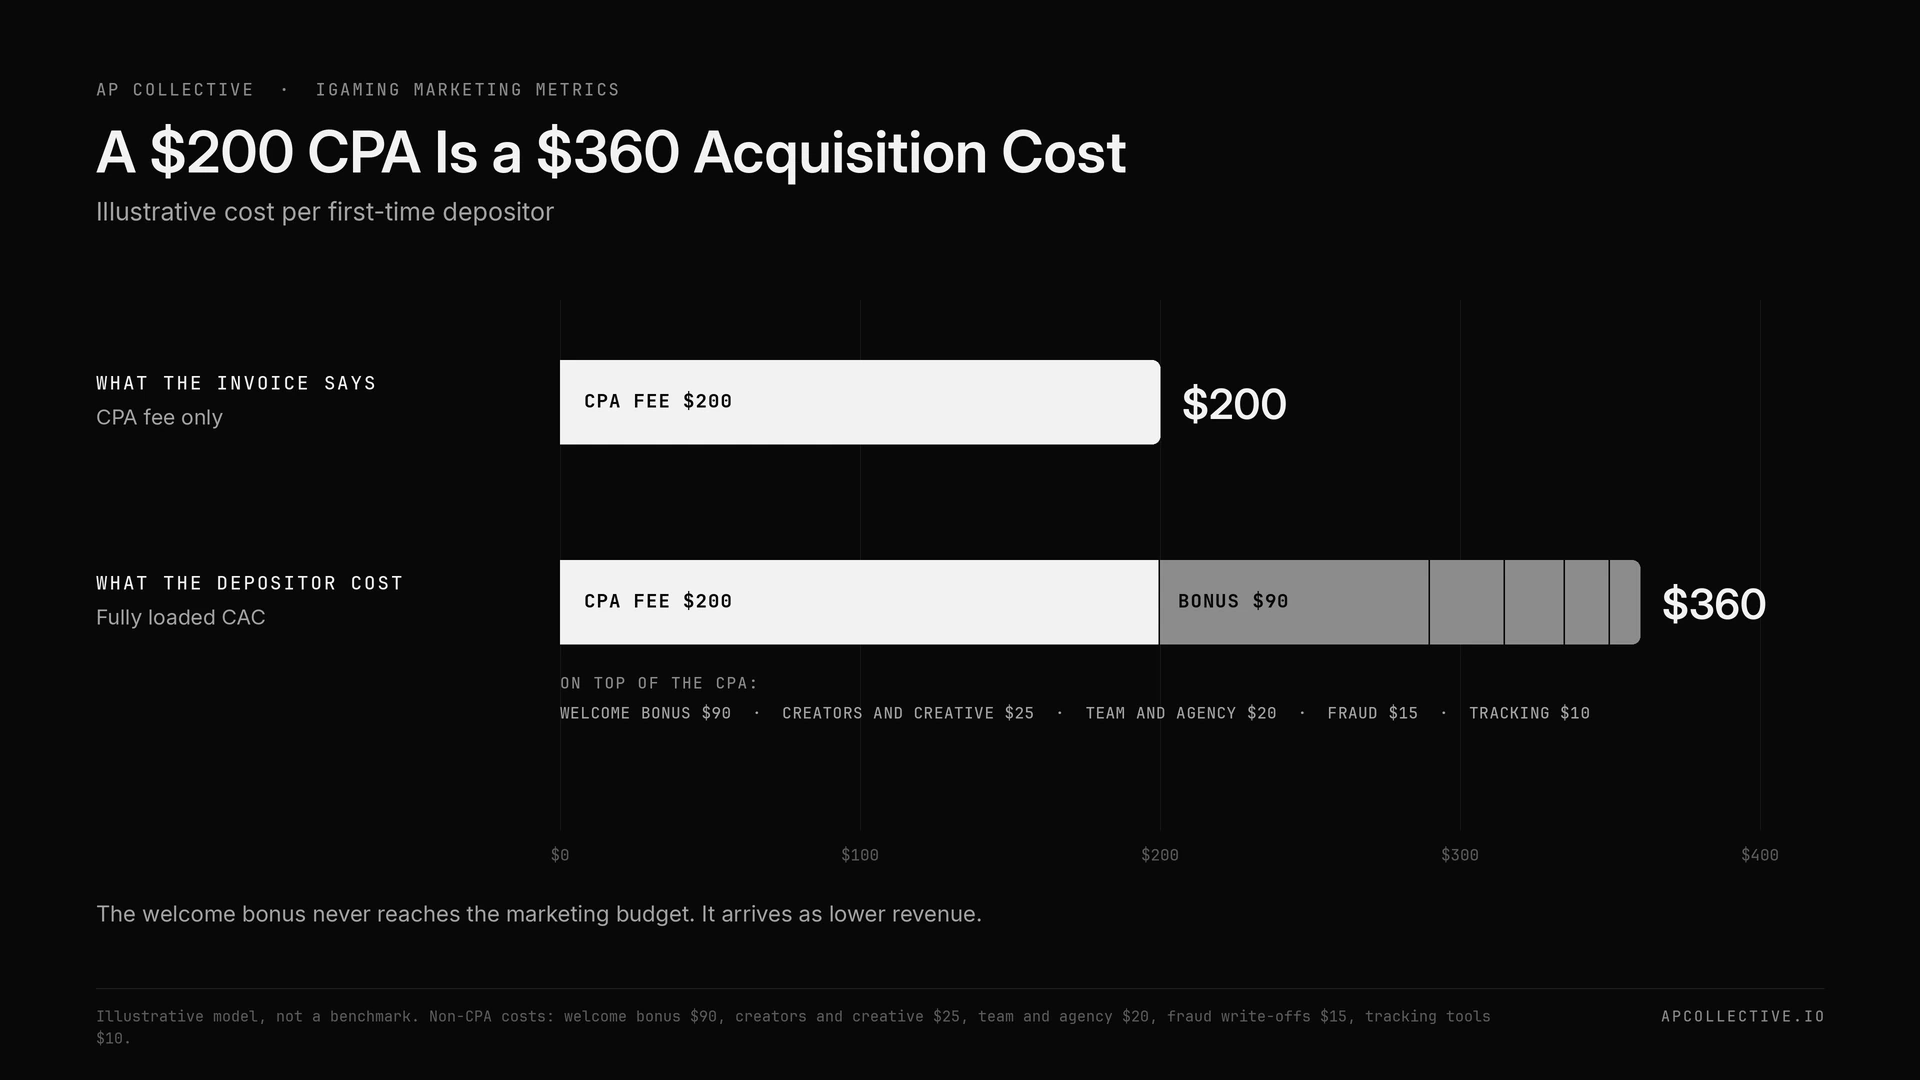 Illustrative iGaming acquisition cost showing a $200 CPA growing to a $360 fully loaded CAC
The $90 bonus line is the one teams forget, because it never touches the marketing budget. It arrives as lower revenue instead.
The same fully loaded logic applies when you weigh creators against paid media, which we set out in our breakdown of crypto KOLs versus paid ads.
AP Collective plans iGaming acquisition on fully loaded CAC, with the welcome bonus and creator fees priced in before a single FTD is bought. Explore user acquisition or book a strategy call.
CPA payback is the first month in which a cohort's cumulative NGR per original depositor, after any revenue share, equals or exceeds its fully loaded CAC. Written as a formula:
Payback month = the first month m in which the sum of NGR per original FTD from month 1 to m, multiplied by (1 minus the revenue share rate), is at least CAC.
The answer is only honest if you get 2 details right.
Expect some months to go negative. When a cohort's players win more than they lose, NGR per FTD drops below zero and the payback line steps backwards. Under revenue share, the contract's carryover clause then decides whether that loss is netted against the partner's future commission, which our guide to how negative carryover works in affiliate deals covers.
Here is an illustrative crypto casino cohort built on the $360 CAC above. NGR per active player rises as casual depositors leave, but the active share falls faster.
Month | Active Share of Cohort | NGR per Active Player | Cumulative NGR per Original FTD |
|---|---|---|---|
1 | 100% | $70 | $70 |
3 | 34% | $120 | $160 |
6 | 22% | $130 | $255 |
8 | 19% | $130 | $306 |
11 | 16% | $135 | $375 |
12 | 15% | $135 | $395 |
18 | 12% | $135 | $502 |
24 | 9.7% | $135 | $588 |
The same cohort pays back at very different speeds depending on how the partner is paid. We modelled 3 deal structures with non-CPA costs held at $160 per FTD and added a downside case in which retention is 20% worse in every month after the first.
Deal Structure | Upfront CAC | Payback, Base Case | Payback, Weaker Retention | Net per FTD at Month 24 |
|---|---|---|---|---|
Pure CPA of $200 | $360 | Month 11 | Month 14 | $228 base, $125 downside |
$80 CPA plus 20% of NGR | $240 | Month 8 | Month 11 | $231 base, $148 downside |
Revenue share of 35% of NGR | $160 | Month 6 | Month 8 | $222 base, $155 downside |
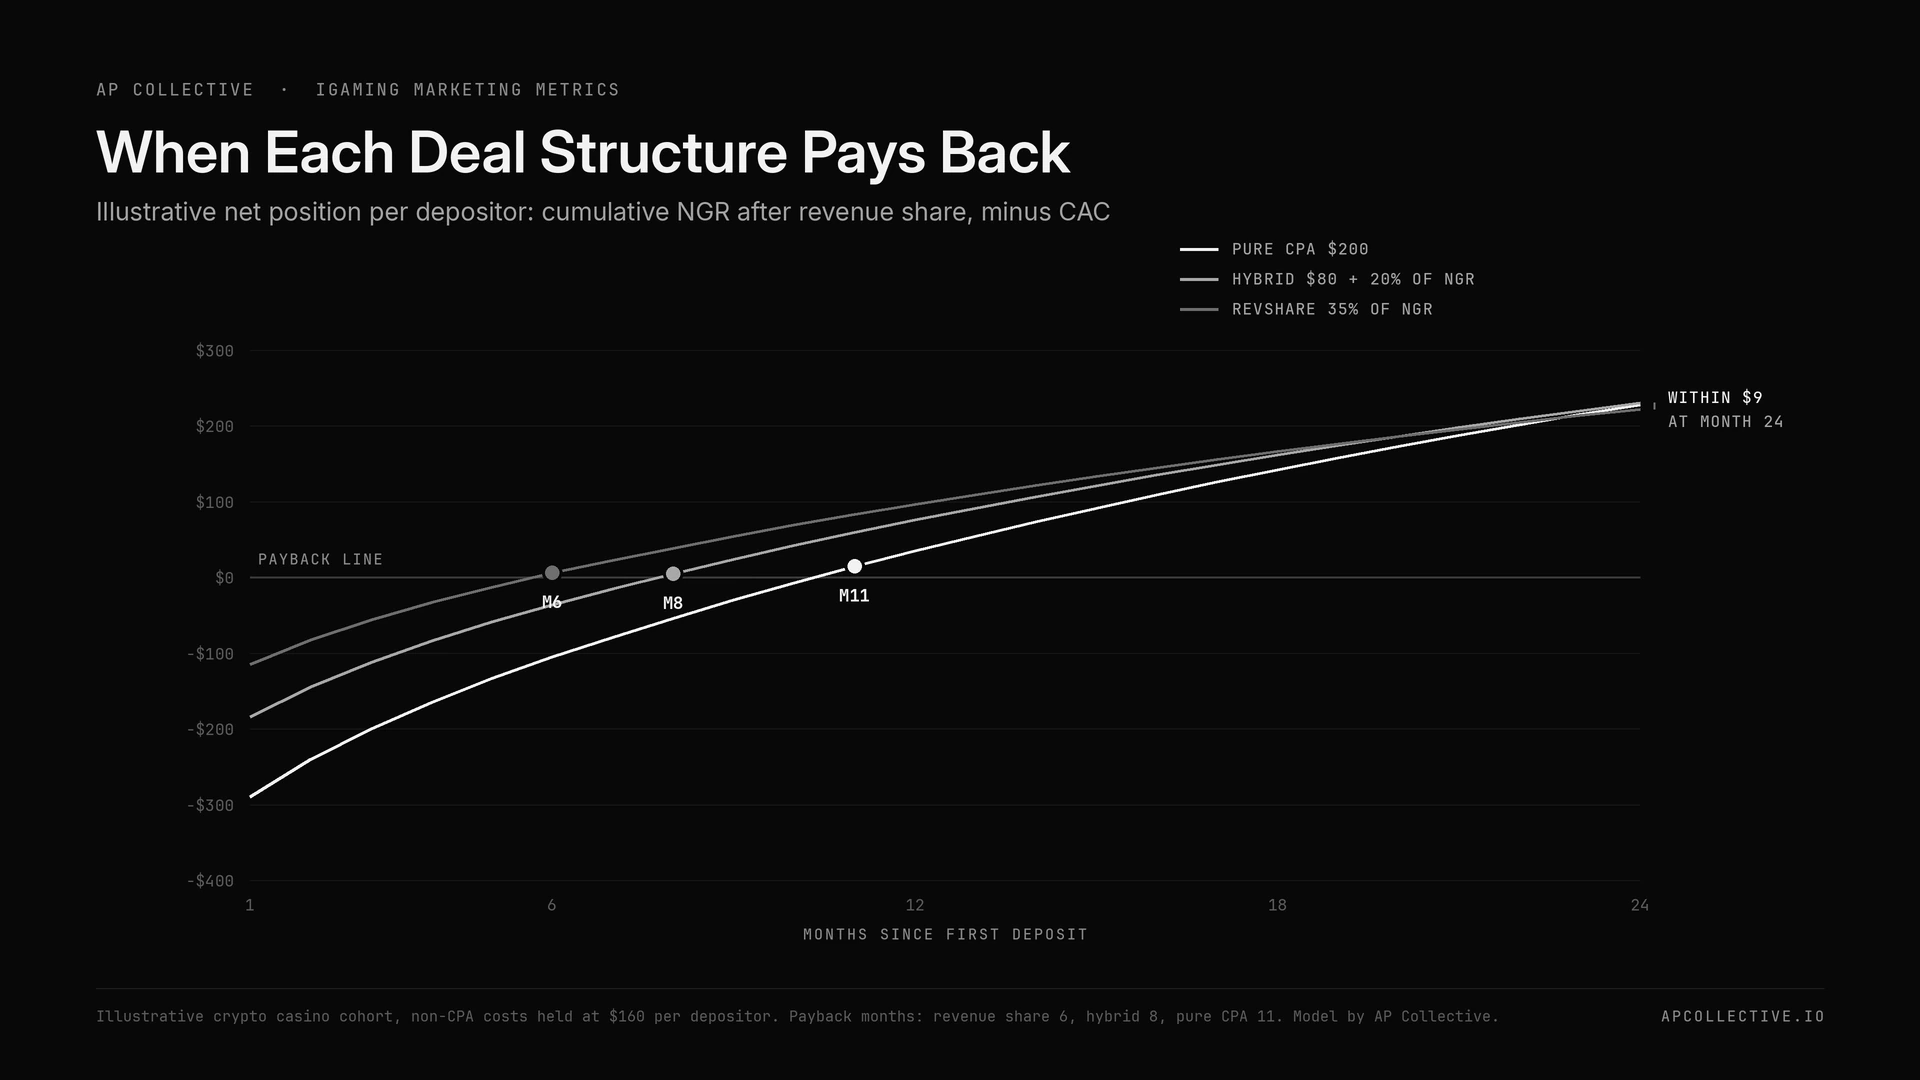 Illustrative CPA payback curves for pure CPA, hybrid and revenue share iGaming affiliate deals
In the base case all 3 structures finish within $9 of each other at month 24. What changes is when the cash comes back and who carries the loss if the cohort churns faster than planned. Pure CPA only wins if retention beats the forecast. The model also has a limit worth naming: it holds player quality constant, which real deals do not, since revenue share partners tend to send players who stay. That is the strongest argument for them.
Public operators can run long payback windows because their balance sheets allow it. DraftKings' chief executive told analysts the company decides acquisition spend "based on our three-year payback rule", on its Q2 2024 earnings call. Few crypto casinos can wait that long. If you fund growth from operating cash, set the payback ceiling first, let it decide the CPA you can afford, then build the budget backwards from it, as in our guide to structuring a crypto marketing budget.
Running the formula backwards gives you that CPA ceiling. Take the running NGR per depositor at your payback ceiling, take off any revenue share and the non-CPA costs, and what is left is the most a CPA can be. On the illustrative cohort with a 12-month ceiling, $395 of cumulative NGR minus $160 of non-CPA costs leaves a maximum pure CPA of about $235.
Sportsbook payback needs a hold adjustment because sportsbook NGR swings with results as well as with player behaviour, so a cohort can look like a failure or a success on the strength of a few weekends.
DraftKings shows the effect across 2 time frames in the same filing. Its sports net revenue margin fell from 8.7% to 6.8% between Q2 2025 and Q2 2026, yet across the first half of each year it barely moved, from 7.4% to 7.3%, per the Q2 2026 results. Michigan's monthly figures swing harder. Online sportsbook adjusted gross receipts fell to $14.6m in March 2025 and reached $64.7m in November, according to the MGCB's March and November releases.
A cohort acquired while bettors' favourite picks keep landing will look like a bad cohort. It may simply be a good cohort that met bad luck early.
So for sportsbook cohorts:
Reading a campaign through The Payback Pairs often reverses the verdict of an FTD report, and a side-by-side comparison of 2 creators shows how. The numbers below are illustrative. A crypto sportsbook runs 2 creators over the same 30 days, with non-CPA costs of $160 per FTD for both. Creator A is a large casino and sports streamer paid a $150 CPA, while Creator B runs a smaller Telegram tipster community, charges $280 and sends far fewer depositors.
Metric at Day 90 | Creator A | Creator B |
|---|---|---|
FTDs delivered | 1,000 | 300 |
CPA | $150 | $280 |
Fully loaded CAC | $310 | $440 |
Median first deposit | $20 | $100 |
Second deposit within 7 days | 18% | 46% |
Active at day 30 | 9% | 31% |
Cumulative NGR per original FTD | $58 | $215 |
Share of NGR from top 5% of FTDs | 71% | 38% |
Projected payback month | Beyond month 24 | Month 8 |
On the FTD report, Creator A wins 1,000 to 300 at barely half the CPA. Every counterpart points the other way. By day 90, Creator B's 300 depositors have produced $64,500 of NGR against $58,000 from Creator A's 1,000, on 43% of the spend. And Creator A's weak average still leans on its top 5% for 71% of NGR, so even the $58 is fragile.
Creator A's profile is what broad audiences tend to produce. In the Patterns of Play account sample, 85% of betting accounts spent less than £200 across a whole year, per iGaming Business, so a big FTD number from a general audience usually means a big number of small players.
The right move is rarely to drop Creator A outright. Put A on a qualifying deposit floor or a hybrid deal that shares the downside, and move the next tranche of budget to B. That decision is invisible in a report that stops at FTDs.
You can judge an iGaming campaign's player quality within 30 days and its economics within about 90, but you cannot confirm payback until the cohort actually crosses its CAC. Most budget mistakes come from asking a later checkpoint's question at an earlier checkpoint.
Checkpoint | What You Can Judge | What You Cannot Judge Yet | Decision It Supports |
|---|---|---|---|
Day 1 | FTD count, median first deposit, device clustering | Player value | Pause obvious fraud |
Day 7 | Second-deposit rate | Retention | Adjust creative and targeting |
Day 30 | Active rate, NGR per FTD, early withdrawals | Payback month | Scale or cut the channel |
Day 90 | Payback trajectory, top 5% share | Lifetime value | Renegotiate the deal structure |
Month 6 to 12 | Actual payback month, share of FTDs paid back | Long-tail value | Set next year's CPA ceiling |
In the illustrative cohort above, the first 90 days delivered 27% of the NGR the cohort produced over 24 months. That is enough to see the trajectory, which is why day 90 is the first checkpoint worth a structural decision. It is still too early to call payback. Listed operators make the point for us: DraftKings works to the 3-year payback rule described on its Q2 2024 earnings call, so month 12 is only a checkpoint for them.
LTV:CAC ratios mislead in iGaming because lifetime value is an average of an extremely uneven distribution, so a handful of high-value players can make a cohort look profitable while most of it never pays back.
The usual advice borrows a 3:1 LTV to CAC target from subscription software, where customers pay similar amounts every month. Gambling revenue does not behave like that. In the Patterns of Play account study of British online gambling, the top 1% of customers by stakes produced 37.4% of operator revenue, the top 5% produced 66.9% and the top 20% produced 89.2%, according to Forrest and McHale's analysis in the Journal of Gambling Studies of 139,152 accounts from 7 operators.
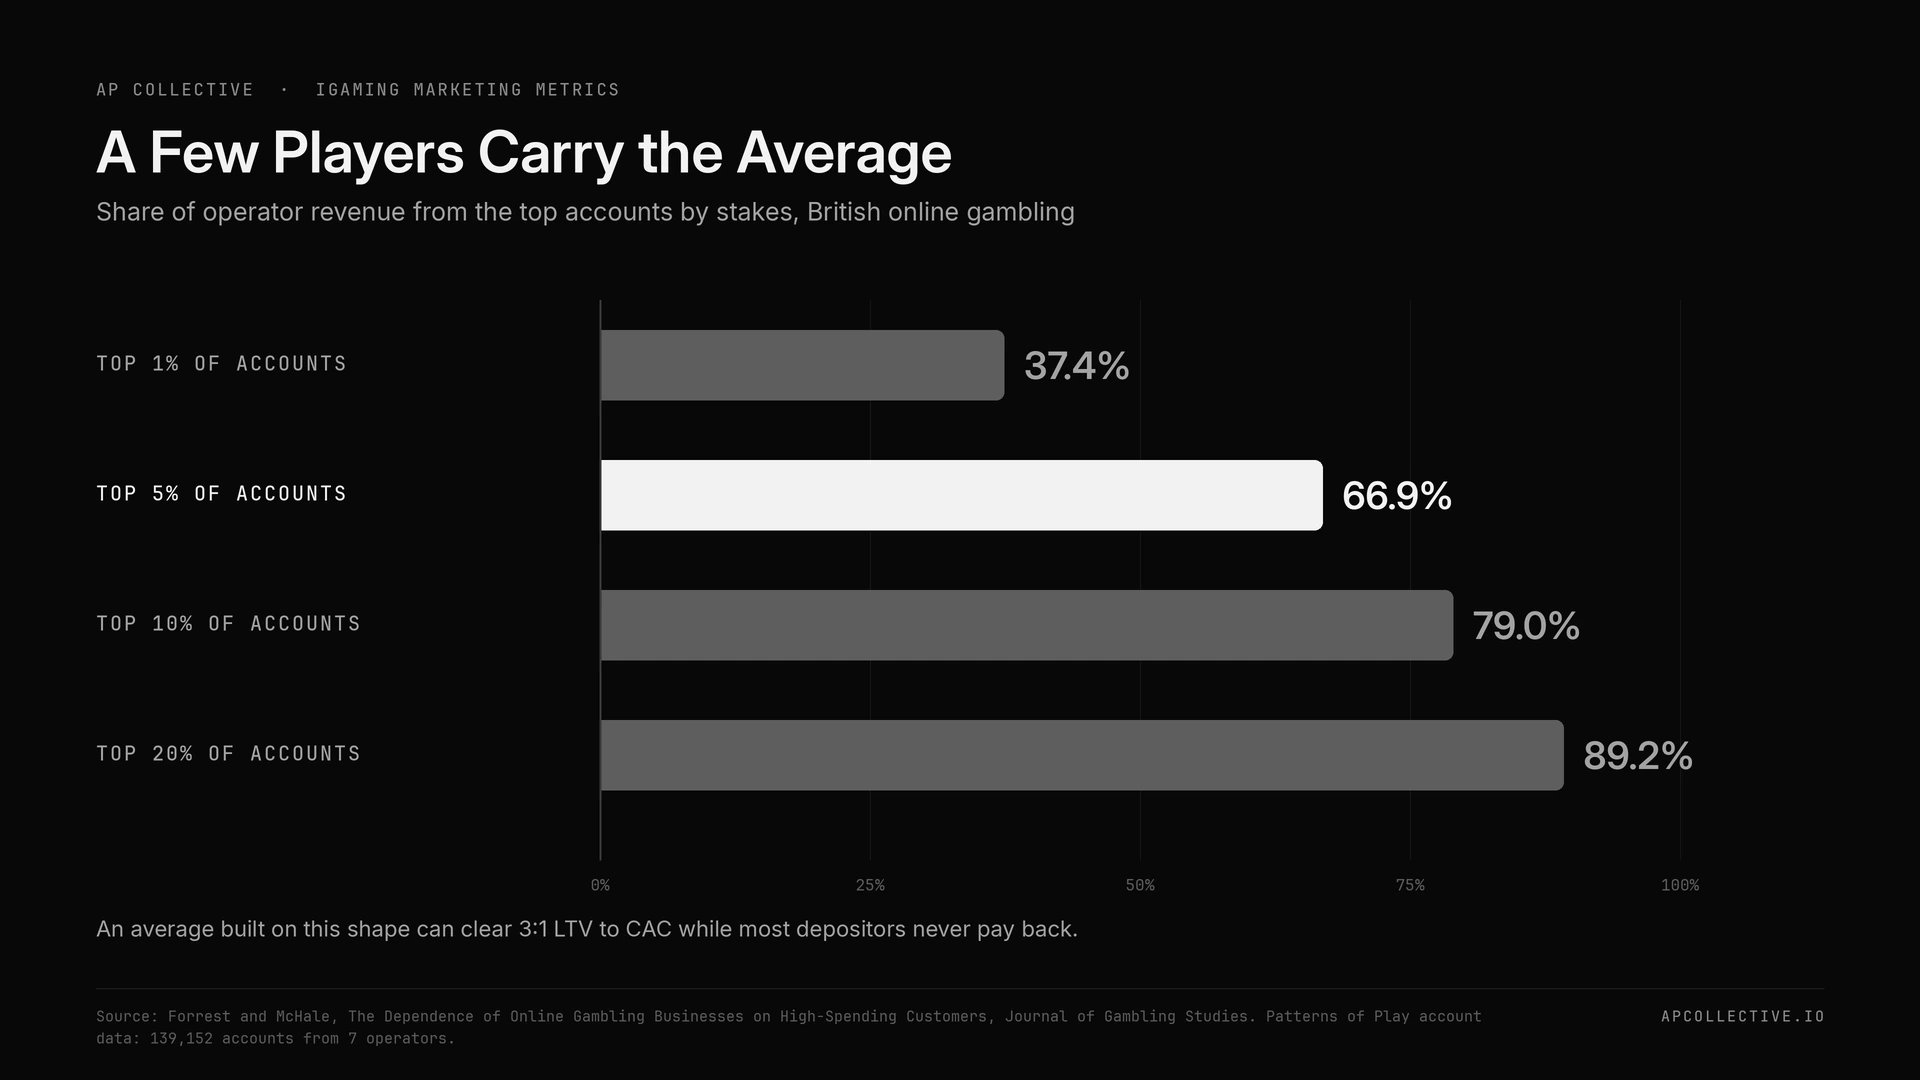 The top 5% of online gambling accounts generated 66.9% of operator revenue in UK data
With that shape, a cohort average can clear 3:1 on the strength of a few players while 9 in 10 depositors never cover their own CAC. So instead of the ratio we report 4 numbers for every cohort:
Now the inconvenient part. The concentration that breaks LTV averages is also where gambling harm concentrates. In the same Patterns of Play data, customers who both bet and played casino games held 25% of accounts but delivered 55% of operator GGY, and breadth of gambling is an established predictor of problem gambling, per NatCen's summary report. A payback model that only works because of the top 1% is a compliance exposure as well as a forecasting one.
If a channel only pays back because of a few high rollers, AP Collective can stress-test the plan for concentration and responsible gambling exposure before spend scales. See compliance and risk or get in touch.
GGR, GGY and AGR describe closely related numbers, and many iGaming reporting disputes are really 2 teams using 2 names for 1 metric or 1 name for 2. Regulators and listed operators each have their own vocabulary, and affiliate contracts add another layer.
The UK Gambling Commission, for instance, asks licensees for gross gambling yield and states in its regulatory returns guidance that operators must report GGY figures "not GGR". The same guidance says loyalty cashback is not deducted from GGY, which is the opposite of how many crypto casino contracts treat rakeback in NGR.
Name You Will See | Where | Closest Standard Metric | Watch For |
|---|---|---|---|
GGY, gross gambling yield | UK Gambling Commission returns | GGR | Loyalty cashback is not deducted |
Gross receipts | Michigan regulator | GGR | Before promotional deductions |
Adjusted gross receipts (AGR) | Michigan regulator | Tax-base revenue | After deductible free play only, capped for casinos |
Revenue | DraftKings filings | Closer to NGR | Incentives already deducted |
Sports Consumer Volume | DraftKings filings | Handle | Includes prediction market trades |
Sports Net Revenue Margin | DraftKings filings | Hold after promotions | 6.8% in Q2 2026 |
NDC, new depositing customer | Listed affiliates | FTD | Counted by the affiliate, not the operator |
MUPs, monthly unique payers | DraftKings filings | Monthly active payers | Counts paid play, not deposits |
ARPMUP | DraftKings filings | Revenue per active payer | $132 in Q2 2026 |
Agree the dictionary before the dashboard: 1 name and 1 formula per metric, written into every partner contract. It is the cheapest fix in this guide.
Each audience for an iGaming report needs a different lead metric, but every audience should see that metric's counterpart on the same page.
Audience | Lead Metric | Counterpart on the Same Page | Cadence |
|---|---|---|---|
Board and investors | Payback month by cohort | Fully loaded CAC and top 5% share | Quarterly |
Finance | NGR by deduction line | GGR and the gross-to-net ratio | Monthly |
Acquisition team | FTD quality by creator and channel | CPA and fully loaded CAC | Weekly |
Affiliates and creators | Qualified FTDs and NGR statements | The contract's deduction list | Monthly |
Compliance | Revenue concentration and safer gambling flags | Channel and creator mix | Monthly |
Most teams skip the last row. Revenue concentration is a commercial risk and a regulatory one at the same time, and regulators already watch the player-protection side. Michigan's regulator received 573 player complaints in 2025 and collected more than $325,000 in fines across 8 violations, with letting players exceed their own wagering limits among the most common breaches, per its 2025 annual report. A marketing report that shows which channels bring in the heaviest-losing accounts is the cheapest way to see that exposure early.
Crypto casinos and sportsbooks run on the same economics as licensed operators, but the observable numbers differ: on-chain deposits stand in for reported GGR, and rakeback does the job welcome bonuses do elsewhere.
Few crypto operators publish GGR, so the market estimates it from deposits. A July 2026 Gambling Insider investigation using public blockchain data counted $22.7bn of 2025 deposits into 12 crypto casinos across Ethereum, BNB Chain and Tron, with Stake alone taking $15.2bn. Most of it arrived as stablecoins. Tron carried more of Stake's money than Ethereum did. The industry convention of about 37 cents of GGR per deposited dollar, tested across a range of 25 to 50 cents, puts those 12 casinos at $5.7bn to $11.4bn of GGR.
Nobody has a better number, including us. The same investigation set Yield Sec's widely cited $81.4bn estimate of 2024 crypto gambling GGR against Tanzanite's figure of roughly $10bn to $11bn, an 8x gap. It also noted that Tanzanite consults for the operators it measures while Yield Sec sells monitoring to governments. Treat every crypto GGR figure, an operator's own included, as an estimate with a method attached.
For a single operator the conversion works the same way. At 37 cents per dollar, $1m of monthly on-chain deposits implies roughly $370,000 of GGR before rakeback and token rewards come off. Move the ratio to 25 or 50 cents and the same deposits imply $250,000 or $500,000, which is why a crypto payback model should always be run at both ends of the range.
Standard Metric | Crypto Casino or Sportsbook | Crypto Exchange | Prediction Market |
|---|---|---|---|
FTD | First on-chain deposit, usually USDT | First deposit, also called FTD | First funded account or first trade |
Handle | Total wagered | Trading volume | Contracts traded |
GGR | Inferred from deposits if unpublished | Trading fee revenue | Fees and spreads |
NGR | GGR minus rakeback, cashback and token rewards | Fees minus rebates and referral commission | Fees minus incentives and liquidity rewards |
CPA | Cost per funded wallet | Cost per funded account | Cost per first trade |
Payback risk | Volatile non-stablecoin deposits | Rebates to high-volume traders | Legal status that varies by state |
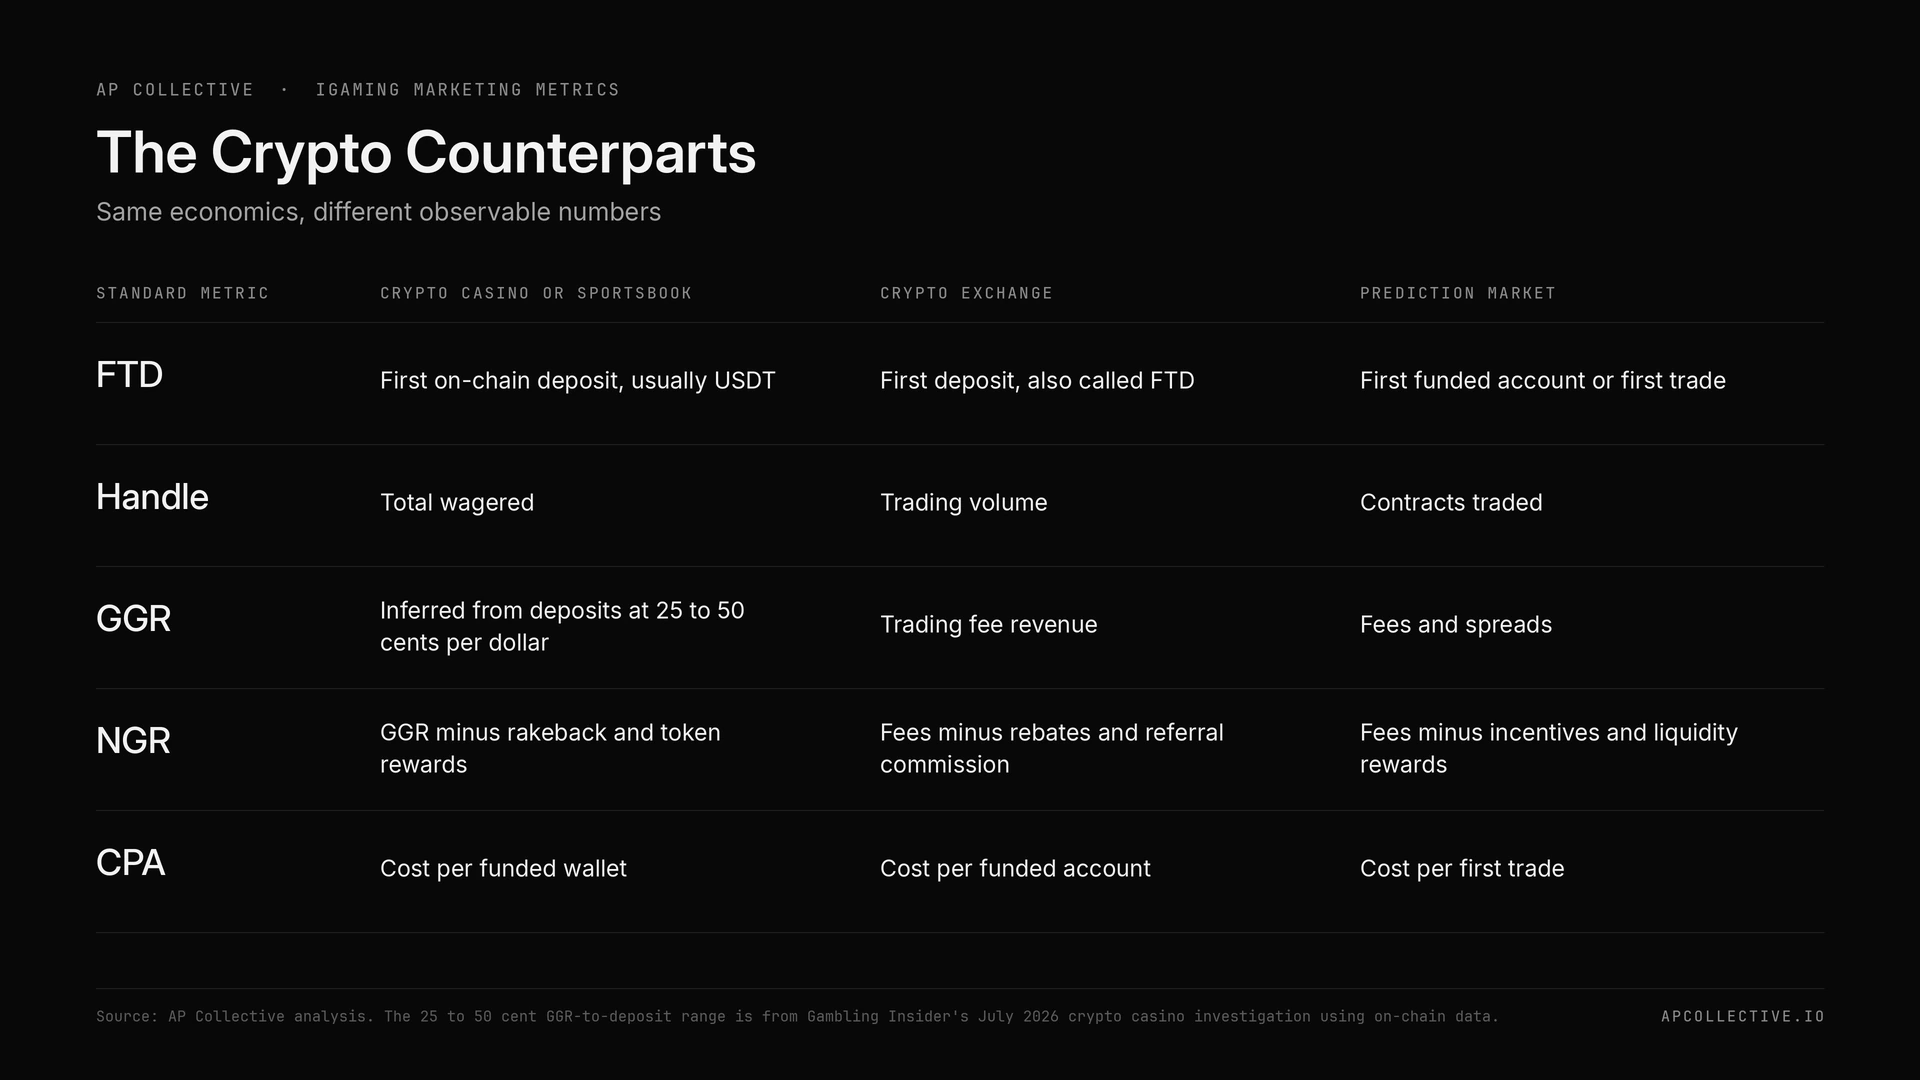 Crypto counterparts for FTD, GGR, NGR and CPA across casinos, exchanges and prediction markets
The Payback Pairs still apply on-chain, with 4 adjustments:
Prediction markets are the newest counterpart. DraftKings launched its Predictions product in December 2025 under CFTC oversight and now counts those trades inside Sports Consumer Volume, per its Q2 2026 filing. For teams building in that category, our prediction markets growth playbook covers the acquisition side.
Running a crypto casino or sportsbook? AP Collective runs creator and streamer acquisition measured in funded wallets and payback months rather than views. See influencer marketing or talk to us.
Run these 8 checks before paying a CPA or revenue share invoice, because each one ties a line on the invoice to the counterpart that proves it. Together they apply The Payback Pairs to a single payment decision.
Check 4 usually carries the most money. On Michigan's online sportsbooks, free play alone moved 35% of gross receipts in 2025, per the MGCB annual report.
Most losing iGaming cohorts looked healthy in the report that approved them because it showed only the first number of each pair and skipped the second. The habits are expensive at scale: reading gross instead of adjusted revenue would have overstated Michigan's 2025 online sportsbook revenue by $235.4m, per the MGCB annual report.
Mistake | Why It Hurts | Better Approach |
|---|---|---|
Reporting FTDs without second-deposit rates | Rewards minimum-deposit farming | Pair every FTD count with 7-day redeposits |
Quoting wagered volume as growth | Bonus play and rakeback inflate it | Report deposits and GGR, with hold |
Comparing revenue share rates across partners | Deduction lists differ by contract | Normalise to a single NGR formula first |
Treating CPA as acquisition cost | Welcome bonuses hide in revenue | Report fully loaded CAC |
Averaging payback over active players | Churned depositors drop out of the maths | Divide by every original FTD |
Mixing gross and adjusted revenue | Michigan's sportsbook gap was 35% in 2025 | Label every revenue line gross or net |
The same discipline applies to any campaign proof you are shown, whether it comes from an agency or a creator. Our guide to reading crypto marketing case studies applies that test to published results.
AP Collective reports iGaming work on payback rather than FTD volume: every creator and affiliate is read through The Payback Pairs before more budget moves to it.
That standard comes from running acquisition across 600+ campaigns and 100M+ users reached, including 5,000+ KOL activations across 100+ projects since 2023. It also comes from exchange programmes such as MEXC's creator network, where the funnel runs on first deposits exactly as a casino's does. For an iGaming client it means:
The honest limit: this approach is slower to produce a headline. If you want a spike of cheap FTDs for a launch announcement, we are the wrong partner.
AP Collective builds full-stack crypto growth for casinos and sportsbooks, from creator distribution through the largest distribution network in Web3 to regional execution and cohort reporting, run as a single system. Start with regional marketing or book a call with the team.
An FTD, or first-time deposit, is a player's first real-money deposit at an online casino or sportsbook. It usually triggers CPA payouts in affiliate and creator deals, and listed affiliates report the same event as NDCs, new depositing customers. On its own, an FTD count says nothing about whether the player deposits again.
A qualified FTD is a first-time deposit that meets the conditions in the affiliate or creator contract, typically a minimum deposit, completed identity checks, some real wagering and a player located in a licensed market. Only qualified FTDs trigger CPA payments, so the qualifying rules decide what an FTD count is really worth.
GGR is stakes minus winnings, the amount players lost. NGR is GGR minus the costs of producing it, usually bonuses, gaming tax, payment fees and other agreed deductions. In Michigan in 2025, free play deductions alone took 35% of online sportsbook gross receipts, before any other cost.
Start with GGR, then subtract every deduction your contract or regulator lists: bonuses and free bets, gaming tax, payment fees, chargebacks, provider fees and, for crypto casinos, rakeback. There is no universal formula, so the deduction list written into the contract is the formula.
CPA, or cost per acquisition, is a fixed fee an operator pays an affiliate or creator for each qualified first-time depositor. It differs from CAC, which adds the welcome bonus, creative, tracking and team costs. In our illustrative example, a $200 CPA became a $360 fully loaded CAC.
Add up NGR per original FTD month by month after any revenue share. The payback month is the first month the running total reaches fully loaded CAC. Divide by every depositor in the cohort, including those who stopped playing, or payback will look shorter than it really is.
It depends on who funds the gap. DraftKings has described a 3-year payback rule, which works for a listed operator with deep reserves. A crypto casino funding growth from operating cash usually needs payback inside 12 months, so set that ceiling first and let it cap the CPA you agree to.
Hold is GGR divided by handle, the share of money staked that the operator keeps. US commercial sportsbooks held about 10.2% in 2025, according to the American Gaming Association. Always check whether a hold figure is measured before or after promotional deductions.
Most iGaming revenue share deals pay on NGR, but the definition of NGR varies from contract to contract. Deals with the same headline rate can pay very different amounts if their deduction lists differ, so compare formulas before you compare rates.
We would not rely on the ratio. iGaming revenue is highly concentrated: in UK account data the top 5% of customers produced 66.9% of operator revenue, so an average LTV can hide a cohort that mostly never pays back. Report the payback month and the top 5% share instead.
They measure closely related things: money staked minus winnings. GGY, gross gambling yield, is the term the UK Gambling Commission requires in regulatory returns. The difference that matters for crypto operators: the Commission does not deduct loyalty cashback from GGY.
Most do not publish it. Analysts estimate crypto casino GGR from on-chain deposits, using roughly 25 to 50 cents of GGR per dollar deposited. A 2026 Gambling Insider analysis estimated $5.7bn to $11.4bn of 2025 GGR for 12 crypto casinos this way.
Any single iGaming metric can be made to look good. Its counterpart is much harder to fake. Report FTDs next to second deposits, handle next to GGR, GGR next to NGR, CPA next to fully loaded CAC and NGR next to the payback month, and the report finally shows whether acquisition made money.
The One-Page Action Spine
David is the Head of Operations at AP Collective. Harvard Business School-certified in Leadership, he has 5+ years of experience in project management and business operations and has led the delivery of over 600 campaigns for 100+ crypto brands since joining AP Collective in 2023. See all our authors here.
Reviewed periodically. If you spot something outdated, write to info@apcollective.io.
This article is educational and does not constitute legal, financial, investment or gambling advice. iGaming is regulated real-money gambling, and operators and their partners must follow the licensing, advertising and responsible gambling rules of every market they serve. Figures marked illustrative are models built for this article, not benchmarks or quotes. Public figures reflect the linked sources as of September 2026. Nothing here promotes gambling to underage or self-excluded people. Gamble responsibly, and market responsibly.
Keep Reading
A restructure takes an afternoon to design and a year to judge. What we learned in the year: change versus transition, the neutral-zone dip, and the 30-90-180 Check.
Why your best people have limits you cannot see, how overload removes capability in a fixed order, and how to plan for sustainable performance instead of maximum utilisation.
Why work falls through the cracks on good teams, what the bystander effect and RACI reveal about ownership, and the Single-Owner Standard we use to fix it.
WHAT'S NEXT
Book a call with the team. No pitch deck required.